The best credit cards based on your answers
Your Guide to Smarter Credit: Find the Right Card for You
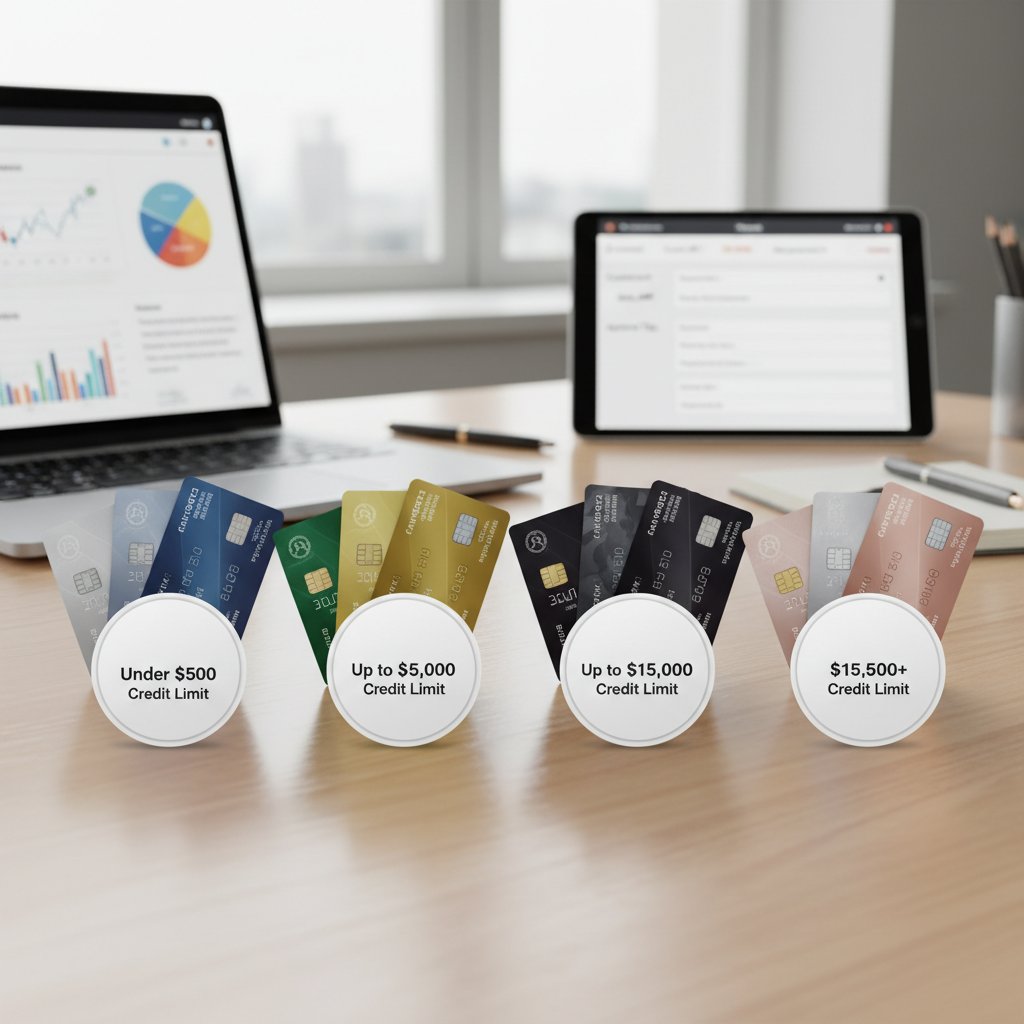
Select a Potential Credit Limit to Begin
Anúncios
Are you still paying for your daily expenses with a card that gives you nothing in return? Many people are, simply because they haven’t explored the latest credit card offers.
You might be missing out on hundreds of dollars in rewards every year without realizing it.
The reality is that the credit card in your wallet could be costing you money through hidden fees and high interest, while others are earning valuable rewards on the exact same purchases. It’s not about spending more; it’s about spending smarter.
This guide is designed to change that. We’ve analyzed the market to identify cards that offer real, tangible benefits.
Forget complex points systems and restrictive categories. We’re focusing on straightforward cash back, interest-free periods, and no annual fees—features that put money back in your pocket from day one.
The Hidden Cost of an Unrewarding Card
Most consumers underestimate the financial drain of a basic, no-frills credit card. It’s not just about a potential annual fee; the true cost lies in the opportunities you miss with every transaction.
Each swipe for groceries, gas, or bills is a moment you could be earning money back.
The problem is compounded by several factors that chip away at your finances over time:
- High Annual Percentage Rates (APR) that make carrying a balance incredibly expensive.
- Lack of rewards, meaning your loyalty to the card issuer goes completely unrewarded.
- Limited benefits that offer little to no real-world value for your lifestyle.
- Foreign transaction fees that penalize you for spending money while traveling abroad.
Think about it: if you spend $2,000 per month on your card, a simple 1.5% cash back credit card would earn you $360 per year. By sticking with a non-rewards card, you are effectively leaving that money on the table.
It’s a silent cost that adds up significantly over the years.
How to Leverage 0% APR Credit Card Offers
One of the most powerful tools available to consumers today is the 0% intro APR credit card. For a promotional period, typically 12 to 21 months, you pay no interest on new purchases or balance transfers.
This feature can be a financial game-changer if used strategically.
Here’s how thousands of savvy consumers are taking advantage of these offers:
- Finance a large purchase: Need a new appliance or a computer? A 0% APR card lets you buy it now and pay it off over time without accruing a single cent of interest.
- Consolidate high-interest debt: If you have balances on other high-APR cards, transferring them to a 0% APR card can save you a substantial amount in interest charges, allowing you to pay down the principal faster.
- Create an emergency fund buffer: Having a 0% APR card on hand can provide peace of mind, giving you an interest-free way to handle unexpected expenses without derailing your budget.
Imagine being able to make a significant purchase and have over a year to pay it off, interest-free. This isn’t a gimmick; it’s a mainstream feature of many of the best credit card offers in 2026 and beyond.
It gives you breathing room and financial flexibility that high-interest cards simply cannot match.
The Power of a No Annual Fee Cash Back Credit Card
The ultimate goal for many is to find a card that pays them to use it, with no upfront cost. This is the promise of a no annual fee cash back credit card.
It’s a simple, powerful financial tool that turns your everyday spending into a source of passive income.
The mechanics are beautifully straightforward. You don’t need to track rotating categories or activate special offers.
With a flat-rate cash back card, you simply earn a consistent percentage back on everything you buy. This simplicity is its greatest strength.
Let’s visualize the impact:
- You use your card for groceries, gas, utilities, and online shopping.
- A percentage of every single transaction is automatically credited back to your account.
- Over a year, this can easily add up to hundreds of dollars without any change in your spending habits.
Many people who switch to a top-tier cash back card are shocked at how much they were leaving on the table. It feels like getting a small raise.
This isn’t just about saving money; it’s about making your financial system more efficient and rewarding. The best part is that it costs you nothing to get started.
Simple Steps to Improve Your Approval Odds
Worried you won’t get approved for a top-tier card? While a high credit score helps, it’s not the only factor issuers consider.
You can significantly increase your chances of approval by taking a few proactive steps. Many people successfully apply for a credit card online by following these simple guidelines.
These habits demonstrate financial responsibility and make you a more attractive applicant:
- Check Your Credit Report: Before you apply, review your credit reports for any errors that could be hurting your score. Disputing inaccuracies is a free and effective way to boost your profile.
- Pay Down Existing Balances: Your credit utilization ratio—the amount of debt you have compared to your credit limits—is a major factor. Paying down balances to below 30% of your limit can provide a quick score boost.
- Maintain a History of On-Time Payments: This is the single most important factor. Even one late payment can have a negative impact, so ensure all your bills are paid on time.
- Avoid Multiple Applications at Once: Each application results in a hard inquiry on your credit report. Spacing out your applications shows lenders you aren’t desperate for credit.
By focusing on these areas, you’re not just preparing for an application; you’re building a stronger financial foundation for the future. Issuers are increasingly looking at the whole picture, and demonstrating these positive habits can make all the difference.
Conclusion: Stop Leaving Money on the Table
You use a credit card for convenience, but it should be doing more than that—it should be working for you. Every day you continue to use a card with no rewards is another day you’re letting potential earnings slip through your fingers.
The choice is simple. You can stick with the status quo, paying for things and getting nothing in return, or you can make a strategic switch to a card that actively rewards you for your spending.
The right card can help you eliminate annual fees, avoid interest charges, and earn real cash back on purchases you were going to make anyway.
This isn’t about changing your habits or spending more. It’s about optimizing your existing financial activity to be more efficient and profitable.
Take the first step today to explore the credit card offers that align with your spending and financial goals. The process to apply for a credit card online is fast, secure, and can unlock a new level of financial benefit.
Credit card offers are subject to issuer approval based on creditworthiness and other factors. Terms, conditions, and fees apply.